The shakeout is clarifying
Every real estate cycle tempts investors to trade their thesis for a forecast. When financing was cheap, almost anything worked; as rates normalized, a lot of what worked stopped working. We think that shakeout is clarifying rather than threatening, because the reason we own manufactured-housing communities and self-storage has never been leverage or a rate call. It is a simpler idea: essential-use real estate where new supply is hard to add tends to compound value patiently, through cycles.
Manufactured housing: demand that stays put
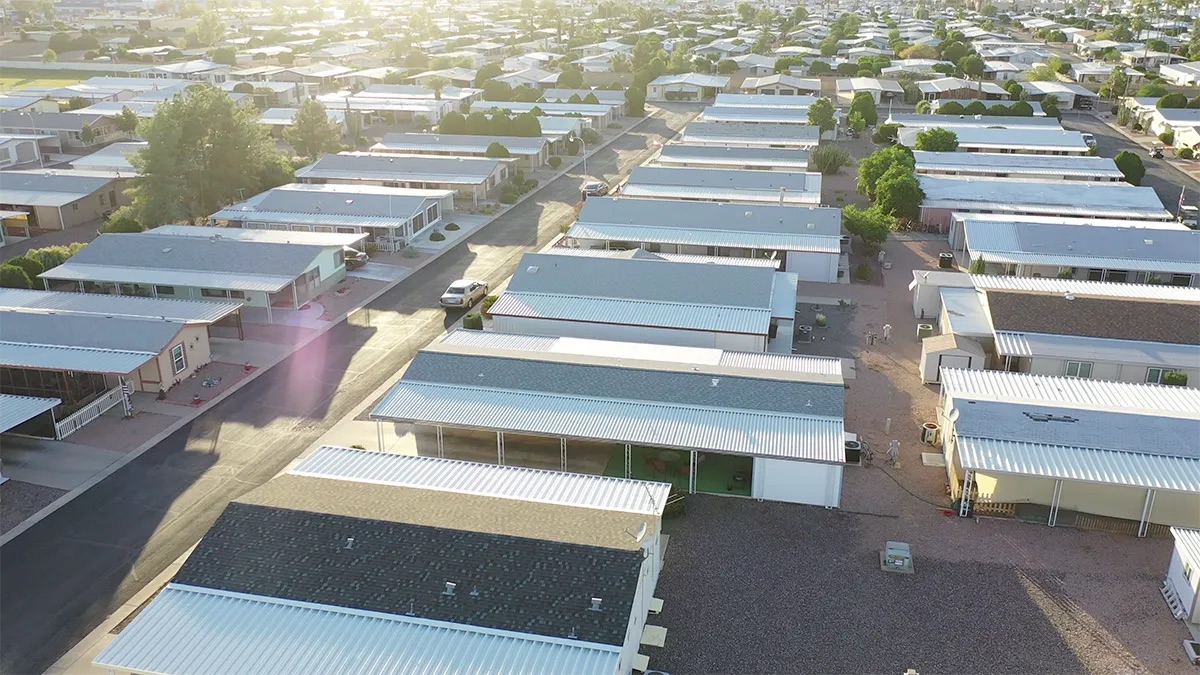
Manufactured housing is widely described as the largest source of unsubsidized affordable housing in the United States, home to roughly 22 million residents.1 That affordability is structural: a manufactured home can cost a fraction of a comparable site-built home per square foot,2 which matters more, not less, when mortgage rates keep site-built ownership out of reach for many households.
The demand side is unusually sticky. In the communities we operate, residents typically own their home and lease the land beneath it. Moving a home is expensive and disruptive, so turnover is low and occupancy is durable. The supply side is the part most investors underestimate: local zoning, entitlement hurdles, and neighborhood opposition make new communities genuinely rare, so the existing stock is difficult to replace at any price.3 Essential demand meeting constrained supply is the whole thesis in one sentence.
First up: local zoning.
One driver at a time, each named somewhere in this article. Sort it onto its side of the thesis. No stakes. Almost no stakes.
Every driver here is stated in the surrounding prose — the game reveals nothing the article does not already say.
Show the work — sources
U.S. Census Bureau, Manufactured Housing Survey (MHS) — average sales price data. https://www.census.gov/programs-surveys/mhs.html
Freddie Mac, "Manufactured Housing: Affordable Homeownership" research. https://www.freddiemac.com/research
Figures attributed to third parties are as of the dates shown and were not independently verified by Freedom Funds.
Self-storage: supply is the swing variable
Storage demand is need-based rather than discretionary — it is driven by the moves, downsizings, divorces, deaths, and small businesses that happen in every economy. What actually moves returns is supply. After a building wave in 2020–2023, new self-storage supply fell to an eleven-year low in 2025, with construction starts down roughly 21% from their 2023 peak as costs and tighter lending made new projects harder to pencil.4 Over the same stretch, sector values corrected about 25% from their post-pandemic peak before pricing began to recover — the trough figure, as carried through trade coverage of Green Street data in the first half of 2026.4 The publisher's own dated number is the one to hold: Green Street's 4 June 2026 index release puts self storage 22% below its 2022 peak, and still second on cumulative value among the twelve property sectors it prices.5
We are candid about the near term. National street rates were still modestly negative year over year in early 2026, and Sun Belt markets that absorbed the most new construction have felt it most.6 That softness is exactly why a disciplined entry basis matters: buying stabilized cash flow below replacement cost, in markets where the forward supply pipeline is thin, is a very different proposition than chasing rents at the top of a cycle.
Show the work — sources
Green Street data as cited in industry reporting on self-storage supply reaching an 11-year low and values roughly 25% off peak at the trough (2025–Q1 2026). Two dates, not two answers: the trough reading and the June 2026 release describe different moments in a recovering market, and each is printed with its own date rather than restated as the other. https://www.greenstreet.com/insights
Yardi Matrix, National Self Storage Report (early 2026) — national advertised street-rate trend. https://www.yardimatrix.com/publications
Figures attributed to third parties are as of the dates shown and were not independently verified by Freedom Funds.
What "compounds" actually means
Compounding is not a marketing word here; it is a description of mechanics. When supply is constrained and demand is essential, operators keep pricing power, and pricing power shows up in net operating income year after year rather than in a single re-rating. Our job is to buy that cash flow at a sensible basis, improve operations, finance conservatively, and let time do the heavy lifting. We would rather underwrite to a margin of safety than to a rate forecast we cannot control.
None of this makes the assets risk-free. Local markets can be oversupplied, financing can tighten, and near-term rents can fall — as recent storage data shows. But the structural features that drew us to these sectors two decades ago are still intact, and downturns tend to widen the gap between disciplined owners and everyone else. That gap, compounded, is the opportunity.
Sources
- Manufactured Housing Institute, "2024 Manufactured Housing Facts / Industry Overview." https://www.manufacturedhousing.org/
- U.S. Census Bureau, Manufactured Housing Survey (MHS) — average sales price data. https://www.census.gov/programs-surveys/mhs.html
- Freddie Mac, "Manufactured Housing: Affordable Homeownership" research. https://www.freddiemac.com/research
- Green Street data as cited in industry reporting on self-storage supply reaching an 11-year low and values roughly 25% off peak at the trough (2025–Q1 2026). https://www.greenstreet.com/insights
- Green Street Commercial Property Price Index, 4 June 2026 release — index level and distance from the 2022 peak by sector (twelve property sectors plus the all-property benchmark). https://info.greenstreet.com/hubfs/GSCPPI-20260604press.pdf
- Yardi Matrix, National Self Storage Report (early 2026) — national advertised street-rate trend. https://www.yardimatrix.com/publications